Foreign investment data often looks more straightforward than it really is. A company sees capital entering from one jurisdiction, identifies the immediate investor and builds a story around that country. Yet the entity providing the funds may be only one layer in a longer ownership chain. The group that ultimately controls the investment may sit somewhere else entirely.
For executives, treasury teams and boards, that distinction is not a statistical curiosity. It changes how they assess concentration, governance, geopolitical exposure and the durability of strategic relationships.
Immediate origin is not the same as ultimate control
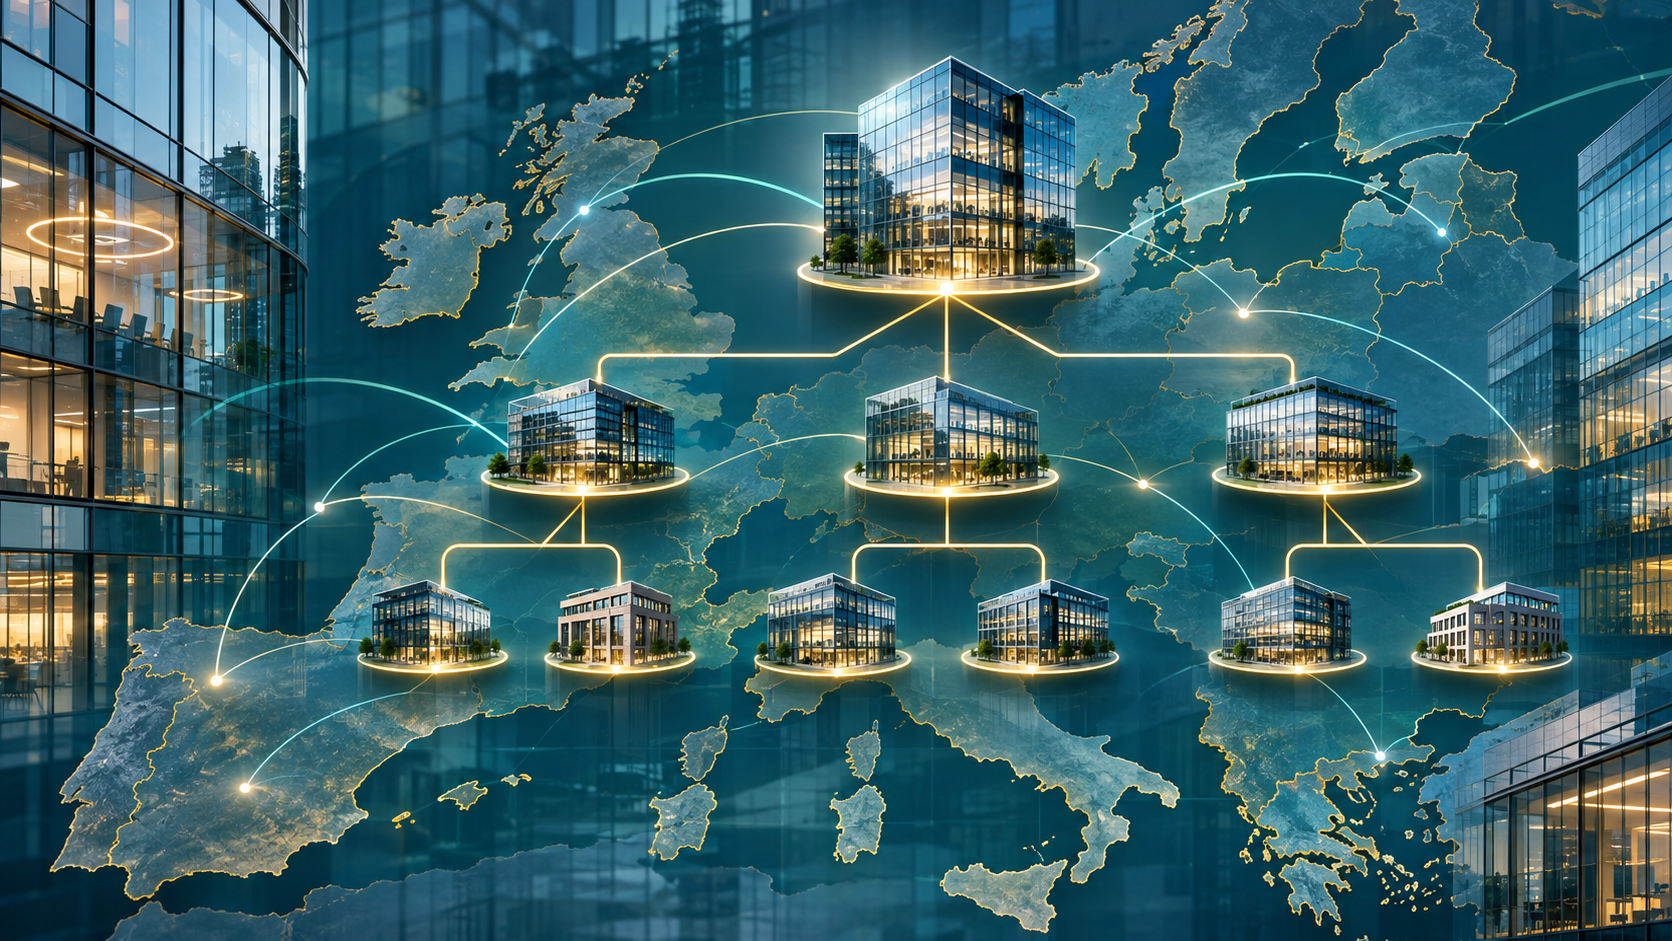
Standard foreign direct investment reporting usually follows the immediate counterparty in a transaction or ownership chain. That view is useful for understanding the legal and financial route through which capital enters an economy. But multinational groups frequently use holding companies, regional headquarters and special-purpose entities. The location of the direct investor can therefore describe the route without fully identifying the decision-maker.
An ultimate-owner view looks beyond intermediate entities to the economy where control ultimately resides. In practical terms, it asks a different question: not merely “where did the funds come from?” but “who ultimately governs the capital and bears the strategic risk?”
Direct investment is generally distinguished from a portfolio holding by the presence of a lasting interest and significant influence, commonly associated with at least 10% of voting power. Even then, tracing control across tiers can be difficult when ownership is dispersed, reorganised or routed through multiple jurisdictions.
Why the distinction matters in the boardroom
First, it improves concentration analysis. A business may appear to have investors from several countries while the ultimate owners are clustered in a much smaller number of economies. A portfolio that looks diversified at the immediate level can be concentrated at the control level.
Second, it sharpens regulatory and sanctions screening. Compliance teams already examine beneficial ownership for individual counterparties, but aggregate investment data can reveal a broader strategic pattern. If a sector depends heavily on ultimate owners from one jurisdiction, a policy change there may affect financing, governance or supply commitments across many apparently separate investors.
Third, it clarifies the role of financial centres. Some economies are important because they host sophisticated legal, tax and financing infrastructure. That is commercially meaningful, but it should not be confused with the final source of control. Both views matter: one explains the channel, the other the underlying ownership.
A better management dashboard
Leaders should avoid replacing one simplistic metric with another. Immediate and ultimate ownership answer different questions and work best side by side. A practical dashboard can separate four layers:
- Transaction route: the jurisdiction of the direct investing entity.
- Ultimate control: the economy of the final controlling owner.
- Operating exposure: where the underlying assets, employees and customers are located.
- Governance rights: voting power, board representation and contractual protections.
This structure helps finance and strategy teams distinguish legal form from economic substance. It also reduces the risk of treating a restructuring between group entities as fresh strategic diversification.
Questions leaders should ask
When reviewing investment exposure, boards can ask whether the company knows both the immediate and ultimate owners of material investors; whether ownership chains have changed since the last review; whether several investors share the same controlling group; and whether the organisation can update its analysis when an entity restructures.
They should also examine data comparability. Ultimate-owner statistics are still developing and may vary by coverage, method and reporting period. Missing information should be labelled rather than filled with assumptions. The goal is not artificial precision, but a more honest map of control.
From compliance task to strategic intelligence
Ownership tracing is often treated as a compliance requirement performed at onboarding. That is too narrow. When updated and aggregated, it becomes strategic intelligence. It can reveal hidden dependencies, support scenario planning and improve conversations with investors, lenders and regulators.
The most useful conclusion is simple: capital has both a route and an owner. Leaders who measure only the route may misunderstand who ultimately shapes the investment. Those who examine both can make better decisions about resilience, partnerships and long-term risk.